Protect yourself from fraud: We will never ask for your password, PIN, or one-time passcode. If something seems suspicious, contact Horizon Bank directly.
Skip to the main content.
Checking
Savings
Buy a Home or Refinance
Get Cash From Your Home
Purchase a Car, RV, or Boat
Borrow Money
Wealth Services
Account Access
Tools and Calculators
Resources
FAQ
Security
Home Equity Line of Credit
The equity you've built can help you make improvements, add new space, or even pay for new adventures.
- Home Equity Lending
- Home Equity Line of Credit (HELOC)
What is a Home Equity Line of Credit?
A Home Equity Line of Credit is a form of revolving credit that allows you to take advantage of the equity you've built up in your home. When you use your home's equity, you're borrowing funds directly from your own equity, then repaying it — usually at a relatively low-interest rate.
Because it acts as a line of credit rather than as a standard loan, you'll have access to funding in any amount (up to the total amount of equity you have) whenever you need it. And you only pay interest on the portion of the home equity line of credit you use.
How Does a Home Equity Line of Credit Work?
With a HELOC, you can access a certain amount of money, up to a predetermined credit limit, over a set period of time, usually 10 years. You can use this money for anything you want, such as home renovations, debt consolidation, or other major expenses. HELOCs can potentially lower your monthly bills and boost your credit score by paying off high-interest credit cards, medical bills, and other debt.
Unlike a traditional loan, you don't receive the entire amount upfront. Instead, you can borrow and repay money as needed within the set time frame. You only pay interest on the amount you borrow, not the entire credit limit.
HELOCs typically have variable interest rates, which means that the interest rate can fluctuate over time based on market conditions. The interest rate on a HELOC is usually lower than other types of loans, such as credit cards or personal loans, but it can still be higher than your mortgage interest rate.
What Are the Benefits of a Home Equity Line of Credit?
Flexibility
With HELOCs you can draw on the line of credit at any time during the draw period, and you only pay interest on the amount you borrow. This means that you can use the funds for a variety of purposes.
Lower Rates
HELOCs typically have lower rates than other types of loans because the loan is secured by your home's equity making it a cost-effective way to borrow and pay off other high-interest debt.
Ease of Application
The application process is simple and straightforward. Before you begin your application, it may be helpful to take a minute and review our home equity document checklist.
How Long Does It Take to Get a Home Equity Line of Credit?
Step 1. Complete a basic application
Apply online in minutes, call 888-873-2640, or visit a Horizon Bank branch.
Step 2. Work with an Advisor
An experienced Horizon Loan Advisor is here to guide you through the process.
Step 3. Close on your HELOC
Once your loan is approved your Loan Advisor will schedule your closing.
Ready to Apply for a Home Equity Line of Credit?
*HELOC Disclosure
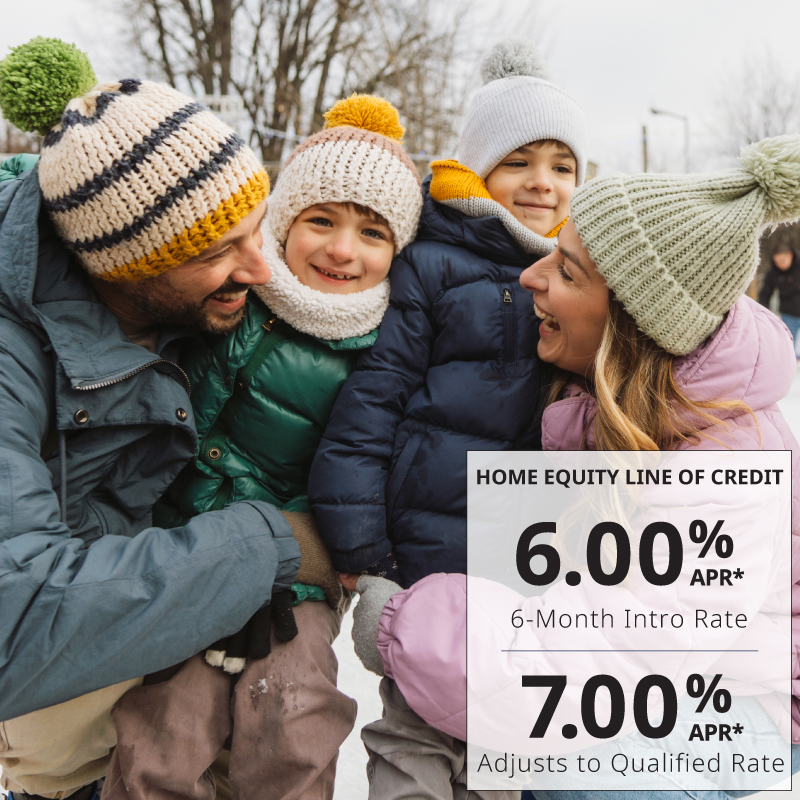
Introductory APR (Annual Percentage Rate) will be fixed at 6.00% APR for the first 6 months for those lines with up to 89.9% loan to value (LTV). Thereafter, the rate may vary. The rate is based on credit score, LTV and Prime Rate + 0.25%. The Prime Rate equals the highest Wall Street Journal (WSJ) prime rate as published in the WSJ effective the date the 6-month introductory period expires. WSJ prime rate effective 12/11/2025 is 6.75%. Example: credit score of 730+ and LTV of 70% or less will have a rate of 7.00% as of date of publication following the introductory period. Maximum rate is 25%. APR will not fall below a floor of 3.25%. Annual fee is $50, waived for first year. Reimbursement fee up to $399 applies if line is closed within the first 36 months. Subject to credit approval. Other terms and conditions may apply and are subject to change without notice. Introductory rate not available on home equity lines of credit opened within the last 12 months unless line amount is increased, and a 25% advance is taken at funding. The 25% advance does not include the payoff disbursement. Offer expires September 30, 2026.
Get Answers to Your Frequently Asked Questions About Home Equity Lines of Credit (HELOC)
-
Why would I want a home equity line of credit?
A HELOC provides you long-term flexibility for both borrowing and repayment, so that you have the financial capability to make the purchases you need to improve your home, buy a new automobile, pay college tuition, or plan for future expenses.
-
How do I access my home equity line of credit?
You can access your home equity line of credit by transferring to your Horizon Bank checking, savings, or an external account or by using your home equity checks mailed to you.
You can also visit your local branch to withdraw from your account, make payments, and obtain account activity. Find a branch near you. -
How do I make a loan payment?
You have several convenient ways to make loan payments:
-
Set up automatic payments within online banking
-
Visits a nearby Horizon branch
-
Visit one of our convenient Video Banking locations close to you.
-
Pay by phone at 888-904-2265 . You may have to pay a convenience fee for this option.
Mail a check to the address below. Please put your loan number in the memo section.
Horizon Bank
P.O. Box 800
Michigan City, IN 46361
-
-
What can I use a HELOC for?
Many people apply for a HELOC to pay for large expenses like these:
-
Remodel and renovate—Remodel your kitchen, get the bathroom you always wanted, add a home gym, professional landscaping, or technology upgrades.
-
Home maintenance—Invest in keeping your house in good shape with a new roof, an energy-efficient furnace, updated windows, and modern plumbing.
-
Debt consolidation—Potentially lower your monthly bills and boost your credit score by paying off high-interest credit cards, medical bills, and other debt.
-
Emergencies—Cover your expenses during a major life event so you can focus on what’s important.
-
Peace of mind—Open a HELOC for fast access to cash when you need it.
-
-
Can I open a HELOC and not use it?
Yes, many people open a HELOC to have cash available for emergencies.
-
Is HELOC interest tax deductible?
In general, the interest paid on a home equity line of credit (HELOC) is tax deductible, but there are some limitations. Consult with a tax professional to determine your specific eligibility for deductions.
-
What is the difference between a HELOC and a home equity loan?
HELOC:
-
Revolving line of credit
-
Borrow against the equity in your home as needed, up to a certain limit
-
Only pay interest on the amount you borrow
-
Interest rates may be variable
-
Typically have a draw period and a repayment period
Home Equity Loan:
-
Lump sum loan
-
Borrow against the equity in your home and receive the full amount upfront
-
Repaid over a fixed term with a fixed interest rate
-
Interest rates may be higher than HELOCs
-
Monthly payments are typically higher than HELOCs
-
-
What is the difference between a HELOC and a cash-out refinance?
Here are the main differences between a HELOC and a cash-out refinance:
HELOC:
-
Revolving line of credit
-
Borrow against the equity in your home as needed, up to a certain limit
-
Only pay interest on the amount you borrow
-
Interest rates may be variable
-
Typically have a draw period and a repayment period
Cash-Out Refinance:
-
Refinance your existing mortgage for more than you currently owe
-
Receive the difference in cash
-
Pays off your existing mortgage and replaces it with a new one
-
Fixed interest rate
-
Monthly payments may be higher than your previous mortgage
-